Multi-family real estate can be an attractive way to build a portfolio, create rental income, diversify assets, or combine a personal residence with investment property.
But a multi-family property is not automatically a good investment simply because it contains more than one unit.
In San Diego, the quality of an opportunity depends on acquisition price, rental income, expenses, property condition, financing, location, tenant profile, future capital needs, and the investor’s long-term strategy.
Sal DeMaria’s real estate practice spans residential property along with multifamily and commercial investment strategy, supported by a prior background in financial planning.
That broader lens is especially useful because investment property should be analyzed as both real estate and a financial asset.
What Counts as Multi-Family Real Estate?
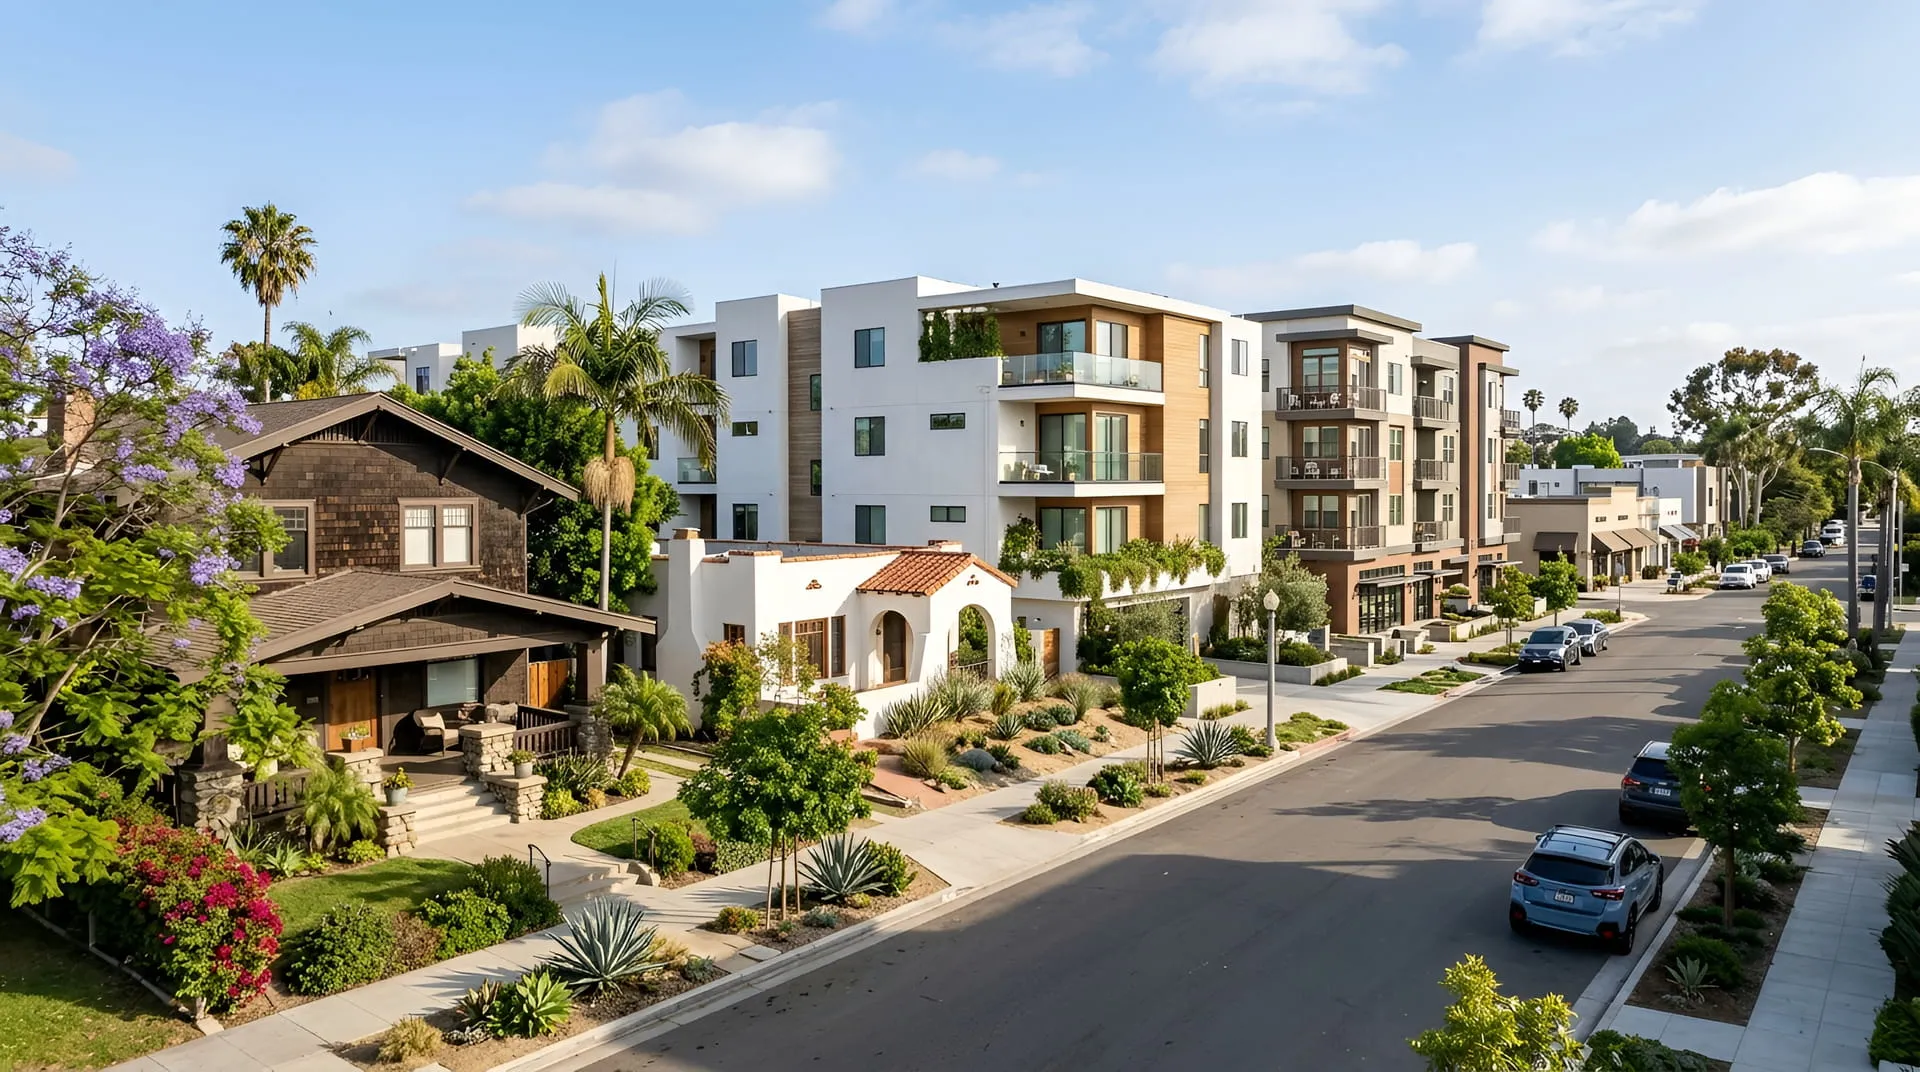
At the small-investor level, multi-family often refers to properties containing multiple residential units.
Examples include:
- Duplexes
- Triplexes
- Four-unit buildings
- Small apartment properties
- Larger apartment buildings
Financing, valuation, management, and regulatory considerations can differ significantly depending on the number of units.
The first step is understanding exactly what type of property you are considering.
Why Investors Consider Multi-Family Property
There are several reasons buyers are attracted to this category.
Multiple Income Streams
Instead of relying on one tenant, the property may generate income from several units.
If one unit becomes vacant, the entire revenue stream does not necessarily disappear.
Economies of Scale
Multiple units under one roof or on one parcel may allow certain expenses to be shared.
Examples can include:
- Roof
- Landscaping
- Exterior maintenance
- Insurance
- Property management
- Common-area systems
Potential for Owner Occupancy
Some investors choose to live in one unit while renting the others.
This can create a different financing and lifestyle strategy than purchasing a fully non-owner-occupied investment.
Long-Term Appreciation Potential
Like other real estate, a well-located multi-family property may benefit from long-term changes in land and property value.
However, appreciation should never be guaranteed in an investment analysis.
Start With the Income
The most important difference between buying a personal residence and buying an investment property is how you evaluate the numbers.
A beautiful building is not enough.
You need to understand the income.
Review Current Rents
Determine:
- Monthly rent per unit
- Lease terms
- Security deposits
- Included utilities
- Parking income
- Laundry income
- Storage income
- Other recurring revenue
Compare current rents with realistic market expectations, but never assume immediate increases are possible without understanding leases and applicable regulations.
Then Understand the Expenses
New investors often underestimate operating costs.
Typical categories may include:
- Property taxes
- Insurance
- Water
- Sewer
- Trash
- Landscaping
- Repairs
- Maintenance
- Property management
- Pest control
- Common-area utilities
- Accounting
- Legal expenses
- Replacement reserves
The exact list depends on the property.
A strong analysis includes realistic assumptions rather than optimistic ones.
Net Operating Income Matters
Gross rent tells you what the property collects.
Net operating income helps show what remains after normal property operating expenses before debt service and certain other costs.
Investors frequently use NOI to compare properties and evaluate value.
But the calculation is only useful if the income and expense assumptions are accurate.
Cash Flow Is Not the Same as Profit
A property can show positive monthly cash flow and still face significant future expenses.
Suppose the roof needs replacement next year.
Or multiple HVAC systems fail.
Or plumbing requires major work.
Investors should plan for capital expenditures rather than treating every dollar of monthly cash flow as spendable profit.
Evaluate the Building Like an Investor
Physical due diligence is essential.
Roof
How old is it?
What is the remaining useful life?
Plumbing
What materials are present?
Has the system been updated?
Electrical
Are panels and wiring appropriate for current usage?
Foundation
Are there signs of movement or repair?
Sewer
Has the line been inspected?
Exterior
What maintenance is approaching?
Units
Which have been renovated?
Are finishes durable?
Parking
Is parking adequate and legally configured?
Utility Metering
Are utilities individually metered or shared?
These questions affect operating performance.
Location Still Matters
A multi-family investment should be evaluated within its neighborhood context.
Consider:
- Employment access
- Transportation
- Walkability
- Schools
- Universities
- Hospitals
- Shopping
- Recreation
- Neighborhood stability
- Development patterns
- Tenant demand
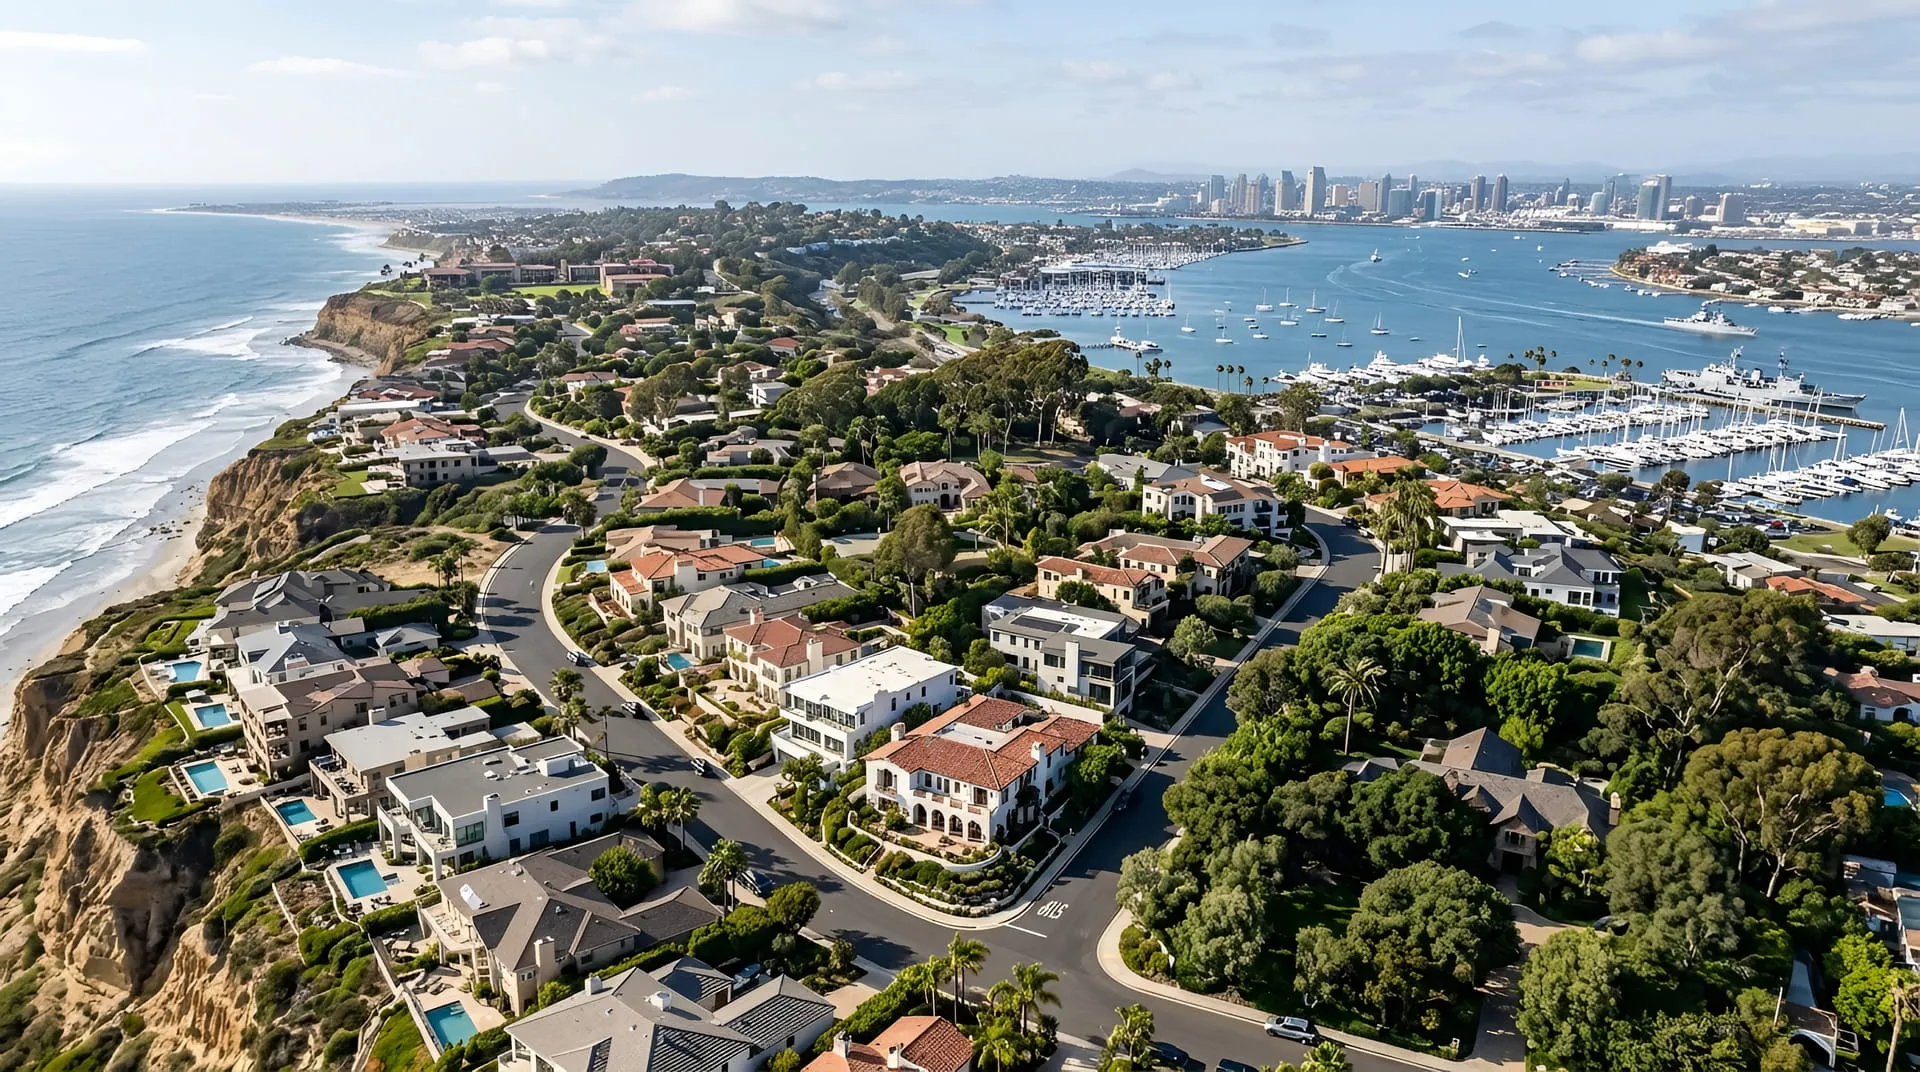
A coastal building and an inland apartment property may have completely different income profiles and expense structures.
Coastal Multi-Family Has Unique Appeal and Risks
San Diego’s coastal neighborhoods can attract strong tenant demand, but buyers should remain disciplined.
Coastal properties may carry:
- Higher acquisition costs
- Greater exterior maintenance
- Salt-air exposure
- Competitive bidding
- Lower initial yields in some cases
The value proposition may rely partly on location and long-term land value rather than immediate cash flow.
Investors should understand which return drivers matter most to them.
Financing Can Change the Entire Deal
Interest rate, down payment, amortization, loan type, and lender requirements can dramatically change cash flow.
Do not analyze the property first and financing later.
They should be evaluated together.
Ask your lender about:
- Down payment
- Interest rate
- Reserves
- Debt coverage
- Appraisal
- Loan term
- Prepayment
- Recourse
- Owner-occupant options where applicable
Use actual financing assumptions rather than generic online calculators.
Consider Your Management Strategy
Who will manage the property?
Self-Management
This may reduce direct management fees but requires time and operational knowledge.
Professional Management
A manager can handle leasing, rent collection, maintenance coordination, tenant communication, and other functions.
Professional management is an expense, but investors should consider its value realistically.
Do not simply remove management costs from your underwriting because you initially plan to self-manage.
Your time has value.
Think in Scenarios
Good underwriting does not rely on one forecast.
Model several.
Base Case
What happens under realistic current assumptions?
Conservative Case
What happens if:
- Rent growth is slower?
- Vacancy increases?
- Repairs rise?
- Insurance increases?
- A major system fails?
Upside Case
What happens if renovations or improved management increase income?
The conservative scenario is particularly important.
Value-Add Opportunities
Some multi-family investors intentionally seek properties that can be improved.
Possible strategies include:
- Renovating units
- Improving common areas
- Adding storage
- Improving landscaping
- Reducing operating inefficiency
- Improving management
- Addressing deferred maintenance
Any proposed physical or operational change should be verified for legal, financial, and practical feasibility.
Do Not Ignore Regulation
Rental property ownership involves legal responsibilities.
Rules can affect:
- Leases
- Rent increases
- Tenant notices
- Evictions
- Security deposits
- Habitability
- Fair housing
- Local property operations
Laws change.
Investors should consult qualified legal and property-management professionals rather than relying on old online information.
How to Decide Whether a Deal Is Actually Good
A strong multi-family acquisition typically makes sense on several levels.
Financially
The numbers support your required return.
Physically
You understand the building condition.
Operationally
You have a realistic management plan.
Strategically
The property fits your investment goals.
Personally
You have sufficient reserves and risk tolerance.
A property can be a good investment for one buyer and a poor investment for another.
Frequently Asked Questions
Is multi-family real estate safer than single-family investing?
Neither is inherently safer. Risk depends on price, leverage, location, condition, tenant demand, management, and investor reserves.
Is cash flow the most important metric?
Cash flow is important, but investors may also evaluate NOI, debt service, capital expenditures, appreciation potential, tax considerations, and long-term strategy.
Should I buy a property with below-market rents?
Potential upside may exist, but investors must understand lease terms and applicable laws before assuming rents can be changed.
Do I need a property manager?
Not necessarily, but investors should understand the workload and legal responsibilities of self-management.
How much cash should I keep in reserves?
There is no universal number. Reserve planning should account for building size, age, systems, financing requirements, and investor risk tolerance.
Build a Real Estate Strategy, Not Just a Portfolio
The goal is not to own the most units.
The goal is to own properties that make sense for your financial objectives.
That requires disciplined analysis, realistic underwriting, thorough physical due diligence, and strong negotiation.
If you are evaluating a duplex, apartment property, or other multi-family opportunity in San Diego, contact Sal DeMaria to discuss the real estate and investment considerations behind the deal.